The biggest mistake parents make when setting up a trust fund is focusing entirely on the money- how much to put in, what assets to include, what age to hand it over- while completely neglecting the structure that determines whether any of it actually reaches their child the way they intended. Specifically, the single most common and most damaging mistake is creating a trust that is never properly funded: the legal document gets signed, and then the actual assets- the house, the bank accounts, the investments- are never retitled into the trust’s name. The trust exists on paper. The money never follows.
That’s the one mistake that renders everything else irrelevant. But it’s far from the only one.
If you’re a parent thinking about setting up a trust fund for your child, or if you already have one and you’re not sure whether it was done right, this guide covers every critical mistake, what each one actually costs, and exactly what to do instead.
Why Trust Funds Aren’t Just for the Wealthy
Before diving into what goes wrong, let’s clear something up: trust funds are not only for wealthy families with multi-million dollar estates. That’s the biggest misconception in this space, and it stops a lot of parents from even exploring the option.
A trust is simply a legal arrangement that lets you control how and when your assets reach your child. You don’t need to be rich to want that control. A trust protects your child whether you’re leaving $50,000 or $5,000,000. It keeps assets out of probate (which can consume 3–7% of an estate’s value in legal fees alone). It keeps your wishes private. And it lets you set terms that a simple bank account or beneficiary designation never can- things like “these funds are for education and housing only” or “distributed in thirds at ages 25, 30, and 35.”
Any parent with a clear intention for how their money should be used after they’re gone has a reason to consider a trust. The mistakes below apply regardless of estate size.
Mistake #1: Creating the Trust But Never Funding It
This is the single most common and most consequential error, and it happens more often than any estate planning attorney will tell you before you’ve already made it.
Here’s what happens: Parents meet with an attorney, sign a trust document, feel a sense of relief, and move on with their lives. The trust exists. But the house is still titled in their individual names. The investment accounts still list them as owners. The bank accounts were never retitled. When they pass away, none of those assets automatically flow into the trust. Instead, they go through probate- the exact expensive, public, time-consuming process the trust was created to avoid.
An unfunded trust is essentially a well-written instruction manual with nothing to instruct. As one estate planning attorney put it: creating a trust document and assuming it’s complete is like installing a new safe in your house and then leaving all your valuables in a cardboard box next to it.
What funding a trust actually requires:
| Asset Type | How to Fund It Into the Trust |
|---|---|
| Real estate | Deed retitled into the trust’s name (requires attorney or title company) |
| Bank accounts | Change account ownership or add trust as beneficiary |
| Investment / brokerage accounts | Retitle with your financial institution |
| Life insurance | Change the beneficiary designation to the trust |
| Retirement accounts (IRA, 401k) | Do NOT retitle — name trust as beneficiary carefully (tax implications apply) |
| Business interests | Transfer ownership via operating agreement or stock assignment |
| Vehicles | Retitle through your state’s DMV (often not worth doing for cars) |
The fix: After the trust document is signed, sit down with your estate planning attorney and go through every significant asset you own. Create a funding checklist. Then actually complete each step- don’t leave it for “later.” Later never comes for as many families as you’d expect.
Mistake #2: Choosing the Wrong Trustee
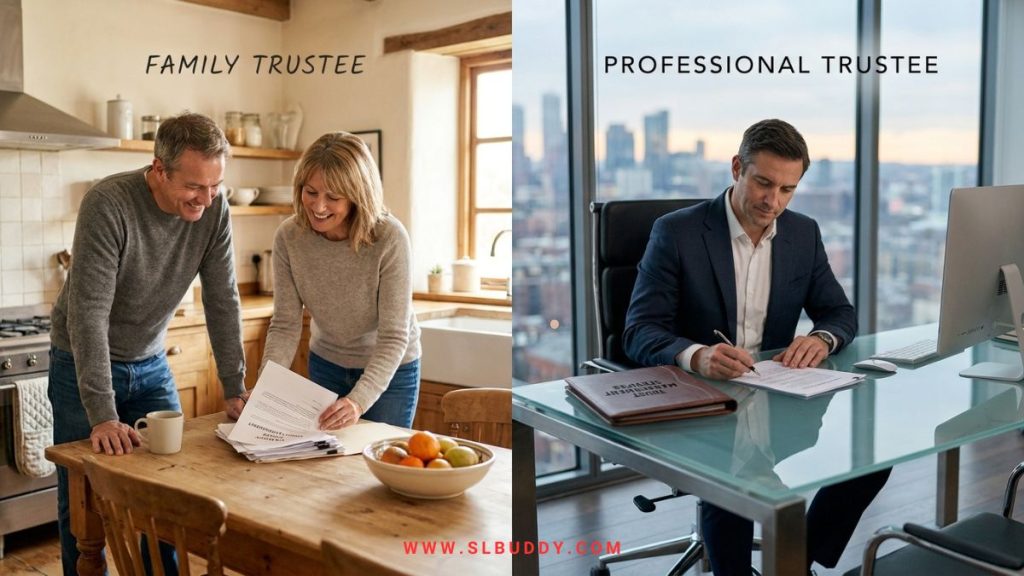
The trustee is the person or institution responsible for managing and distributing the trust’s assets according to your instructions. This person will have legal authority over everything your child stands to inherit. And yet most parents choose a trustee the same way they’d choose a dinner guest, based on closeness, not capability.
Choosing a family member feels natural. They love your child. They know your values. They’ll do right by your kids. These are things parents tell themselves, and they’re not wrong, exactly. But love and financial/legal competence are completely different qualifications. A trustee needs to:
- Manage and invest trust assets prudently over potentially decades
- File annual tax returns for the trust
- Keep detailed records of every distribution
- Navigate potential conflicts between beneficiaries
- Enforce distribution terms even when beneficiaries push back
- Remain impartial when family dynamics get complicated
A sibling who loves your children deeply but has no financial background, limited time, and their own family pressures is not necessarily equipped for that role. And if they get it wrong- if assets are mismanaged, records aren’t kept, distributions are made inconsistently- there’s very little recourse that doesn’t involve an expensive legal dispute within your own family.
Individual trustee vs. professional/corporate trustee:
| Factor | Individual (Family/Friend) | Professional/Corporate Trustee |
|---|---|---|
| Cost | Usually free | Annual fee (0.5–1.5% of assets typically) |
| Personal knowledge of child | High | Low unless they specialize in families |
| Financial expertise | Variable | High |
| Impartiality | Often compromised | Legally required |
| Availability over decades | Uncertain | Continuous |
| Accountability | Informal | Legally bound and regulated |
| Risk of conflict | High in family dynamics | Low |
The fix: Think about who you would trust to manage a small business on behalf of your child for the next 20–30 years. That’s the standard. If no individual in your life meets it, a professional or corporate trustee or a co-trustee arrangement where a family member and a professional share the role may be the right answer. Many trust companies now offer services scaled to modest-sized trusts, not just large estates.
Always name a successor trustee as well. If your primary trustee becomes incapacitated, dies, or simply can’t continue, the trust needs someone to step in without court intervention.
Mistake #3: Thinking Only About Money, Not About Purpose
Here’s something estate planning attorneys hear regularly from parents after a trust has been set up: “I just want to make sure my child is taken care of.” It sounds complete. It isn’t.
What does “taken care of” actually mean? Does it mean covering tuition? A home down payment? Living expenses if they face hardship? Investment capital if they start a business? All of the above? With no strings attached?
A trust without a clearly articulated purpose becomes a blank check with delayed delivery. If the trust documents don’t specify why distributions should be made, the trustee has little guidance, and your child has little protection from their own potential financial immaturity.
The most thoughtful trust documents don’t just specify when a child can access funds- they specify what for and sometimes under what conditions. These are called distribution standards, and they’re among the most important and most overlooked elements of trust planning.
Common distribution structures:
- Age-based: Child receives funds at set ages (e.g., one-third at 25, half the remaining balance at 30, everything at 35). Simple but doesn’t account for life circumstances.
- Milestone-based: Distributions tied to completing a degree, maintaining employment, buying a home, starting a business. More aligned with life outcomes.
- Needs-based with trustee discretion: Trustee has authority to distribute for health, education, maintenance, and support (the HEMS standard). Flexible but depends on trustee judgment.
- Incentive provisions: Some trusts match earned income, or provide a distribution when a child demonstrates financial literacy. Controversial but effective for certain families.
- Lifetime trust: Assets remain in trust for the child’s lifetime, protecting from divorce, creditors, and poor decisions. More common for substantial inheritances or children with special needs.
Wells Fargo’s estate planning guidance notes that “giving children too much access too soon can undermine the protections a trust is designed to provide” and that if funds are released outright while a child faces divorce, addiction, or financial immaturity, “those funds are fair game.”
The fix: Before finalizing any trust document, spend real time answering these questions:
- What do I actually want this money used for?
- What life decisions do I want it to support?
- At what point is my child mature enough to manage a lump sum?
- Are there circumstances where I’d want to restrict access?
- Are there circumstances where I’d want the trustee to have maximum flexibility?
Your answers should be in the trust, not just in your head.
Mistake #4: Not Understanding the Tax Implications
Trust funds and taxes are intertwined in ways that catch a surprising number of parents off guard. The good news for 2026 is that the federal estate tax exemption has increased significantly. The less obvious news is that the tax picture is more complicated than most parents realize.
What you need to know for 2026:
As of January 1, 2026, the federal gift and estate tax exemption has increased to $15,000,000 per person $30,000,000 for married couples) under the One Big Beautiful Bill Act. The annual gift tax exclusion remains $19,000 per recipient.
This means the vast majority of American families will never owe federal estate tax. But that doesn’t mean taxes aren’t a concern.
Trust income tax is where parents get surprised. Unlike individual taxpayers, trusts reach the highest federal income tax rate of 37% very quickly after just $16,250 of trust income in 2026. On top of that, a 3.8% net investment income tax applies to trust income above $16,000, creating a combined rate of up to 40.8% on ordinary income. Compare that to an individual taxpayer who doesn’t hit 37% until income exceeds several hundred thousand dollars.
This matters enormously for how trust assets are invested and distributed. A trust that accumulates income internally pays far higher taxes than one that distributes income to the beneficiary who may be in a much lower bracket.
State taxes matter too. Some states have their own estate or inheritance taxes with thresholds well below the federal level. New York’s estate tax exemption, for example, is $7,350,000 in 2026, and it applies a “cliff” rule where an estate worth more than 105% of the threshold loses the exemption entirely. Parents with significant real estate in high-tax states need state-specific planning, not just federal.
Retirement accounts need special handling. IRA and 401(k) accounts should generally not be retitled into a trust directly. The tax implications are significant and complex. Naming a trust as the beneficiary of a retirement account requires careful drafting to preserve the tax-deferred benefit for your child.
The fix: Work with both an estate planning attorney and a tax advisor. These are different professionals with different expertise. The attorney drafts the trust; the tax advisor helps structure it for maximum efficiency. Trying to collapse this into a single conversation or, worse, skipping professional guidance entirely is where tax mistakes get made.
Mistake #5: Setting Terms That Are Too Rigid or Too Loose
The terms of a trust are its operating instructions. Get them wrong in either direction and the trust fails your child in different but equally damaging ways.
Too rigid: A trust that only distributes funds for college tuition offers no help if your child pursues a trade, starts a business straight out of high school, or faces a medical emergency. Distribution terms written in the 2020s need to account for a child’s life in the 2040s and 2050s, a period parents genuinely cannot predict.
Too loose: A trust that gives the trustee complete discretion with no guidance or that hands over assets outright at a young age offers no real protection. A 22-year-old inheriting a significant sum outright is statistically likely to manage it poorly, regardless of upbringing. Research consistently shows that sudden access to inherited wealth negatively affects the financial behavior and life motivation of young adults who weren’t prepared for it.
The middle ground that works:
- Use HEMS language (Health, Education, Maintenance, Support) as a baseline standard for trustee discretion; it’s flexible enough to cover most real-life needs while providing legal guidance.
- Include a hardship provision that allows the trustee to make emergency distributions outside the normal terms.
- Set tiered distributions rather than a single lump sum.
- Consider including an “incentive match” for earned income during your child’s younger adult years, which maintains their motivation to work while supplementing their income.
- Give the trustee genuine discretion, but pair it with a “letter of intent” a non-binding document that explains your values, your wishes, and what you hoped the trust would accomplish. This isn’t legally enforceable, but it guides the trustee’s judgment in ways the legal document alone cannot.
Mistake #6: Forgetting to Include Asset Protection Provisions
One of the most valuable features a trust can offer is protection from creditors, divorcing spouses, lawsuits, and financial misfortune. But only if that protection is deliberately built in. Many parents skip this because they assume the trust itself is protective- it isn’t, automatically.
Without specific protective language, trust assets can be exposed in ways that defeat the entire purpose of the trust:
- If your adult child gets divorced, inherited assets in certain trust structures can be considered marital property in some states.
- If your child faces a lawsuit or business failure, unprotected trust assets may be reachable by creditors.
- Without a spendthrift clause, beneficiaries can in some cases assign their interest in the trust to someone else including creditors.
A spendthrift clause prevents beneficiaries from voluntarily or involuntarily transferring their interest in the trust before they actually receive it. It’s one of the most important protective tools in trust drafting, and it costs nothing to include. Yet it’s routinely omitted from template-based or DIY trust documents.
The fix: Ask your estate planning attorney specifically about spendthrift provisions, asset protection trusts, and how your state treats inherited assets in divorce proceedings. These vary significantly by state.
Mistake #7: Never Updating the Trust After Life Changes
A trust written today should reflect your life as it exists today. Five years from now, when circumstances have changed- a new child is born, a marriage ends, a beneficiary develops a substance problem, you buy or sell a business, tax laws shift- the old terms may no longer reflect your intentions at all.
Most parents review their trust exactly once: the day they sign it. That’s a problem.
Triggers that should prompt a trust review:
| Life Event | Why It Matters |
|---|---|
| Birth of another child | New beneficiary may not be named |
| Death of a beneficiary or trustee | Successor designations need review |
| Divorce (yours or a beneficiary’s) | Distribution terms may need adjustment |
| Major change in asset value | Funding levels and distribution percentages shift |
| Change in tax law | Exemptions, rates, and strategies evolve |
| Child develops special needs | Separate special needs trust may be warranted |
| Trustee becomes unavailable | Successor trustee must be confirmed and willing |
| Moving to a different state | Trust must comply with new state’s laws |
For revocable trusts, plan to review every 2–3 years at minimum, and immediately after any major life event. For irrevocable trusts, changes are more restricted, which is exactly why getting the initial terms right matters so much.
The fix: Put a recurring calendar reminder. Treat your trust like you treat your will- not as something written once and filed away forever, but as a living document that needs to keep up with your life.
Mistake #8: Going the DIY Route on a Document That Matters This Much
Online trust templates have made it easier than ever to put something on paper and call it a trust. And for very simple situations, some of these tools are legitimate. But the most common trust fund mistakes- failing to fund the trust, choosing the wrong structure, missing asset protection provisions, incorrect retirement account handling, failing to account for state-specific laws- are precisely the mistakes that DIY documents don’t catch.
The cost of a properly drafted trust by an estate planning attorney typically ranges from $1,500 to $5,000 depending on complexity and location. That’s a one-time expense. Compare it to the cost of a trust that goes through probate anyway, or one that triggers a family dispute, or one that creates an unexpected tax bill for your child.
Working with a professional doesn’t mean you hand over control. It means you have someone whose job is to ask you the questions you didn’t know you needed to answer and to translate your intentions into language that actually holds up.
What a Well-Structured Trust Actually Looks Like
Here’s what the combination of avoiding all these mistakes produces: a trust that:
✅ Is funded on the day it’s signed, with a clear asset inventory and retitling plan
✅ Names a trustee chosen for competence, not just relationship
✅ Includes a named successor trustee (and a backup)
✅ Has clearly written distribution standards tied to purpose, not just age
✅ Includes a hardship provision for flexibility
✅ Includes a spendthrift clause for creditor protection
✅ Has been structured with both estate and income tax efficiency in mind
✅ Is reviewed on a schedule and updated after major life events
✅ Is accompanied by a letter of intent that explains your values to the trustee
That’s not an unrealistic standard. It’s what a straightforward, well-planned trust looks like when set up correctly from the start.
Trust Types: Choosing the Right Structure
Parents who are ready to set up a trust also need to choose the right type. The most important foundational choice is this:
| Revocable Trust | Irrevocable Trust | |
|---|---|---|
| Can it be changed? | Yes — at any time | Generally no, or very difficult |
| Estate tax benefit? | No — assets remain in your estate | Yes — removes assets from taxable estate |
| Creditor protection? | Limited | Strong (with proper drafting) |
| Probate avoidance? | Yes | Yes |
| Control over assets? | Retained by grantor | Transferred to trustee |
| Best for | Most families starting out | High-net-worth planning, asset protection, special needs |
Beyond this, there are specific trust types designed for particular goals:
- 2503(c) Minor’s Trust: Allows annual gifts to qualify for the $19,000 gift tax exclusion, but the child receives full control at 21.
- Crummey Trust: Similar tax benefit but without mandatory access at 21; more flexible for parents who want to delay distribution.
- Special Needs Trust: Designed to provide for a child with disabilities without disqualifying them from government benefits like Medicaid or SSI.
- Testamentary Trust: Created within a will, comes into effect at death. Simple but goes through probate first.
- Dynasty Trust: Structured to transfer wealth across multiple generations with minimal estate tax erosion. More relevant for substantial estates.
Action Steps: What to Do Right Now
Whether you’re starting from scratch or reviewing an existing trust, here’s your checklist:
If you don’t have a trust yet:
- Schedule a consultation with an estate planning attorney (not a general practice lawyer; a specialist matters here).
- Think through your answers to the purpose questions in Mistake #3 before that meeting.
- Make a complete inventory of your assets before the meeting.
- Research two or three potential trustee candidates- individual and professional.
- Review your state’s estate tax rules separately from federal rules.
If you already have a trust:
- Pull out the document and check when it was last updated.
- Verify that every major asset is titled in the trust’s name or properly designated.
- Confirm your trustee is still able, willing, and appropriate.
- Check that your successor trustee designation is current.
- Review the distribution terms- do they still reflect what you actually want?
- Schedule a review meeting with your attorney if it’s been more than 2–3 years.
The Bottom Line
The biggest mistake parents make when setting up a trust fund isn’t choosing the wrong investment inside the trust, or miscalculating how much to put in. It’s treating the legal document as the finish line when it’s actually just the starting point. A signed trust that isn’t funded is worthless. A funded trust with the wrong trustee is dangerous. A well-structured trust that’s never updated is a time bomb.
Setting up a trust fund for your child is one of the most meaningful things you can do for their financial future. Done right, it protects what you’ve built, reflects what you believe, and gives your child a foundation that outlasts any single financial decision they’ll ever make. Done carelessly, it creates exactly the kind of confusion, expense, and family conflict it was supposed to prevent.
Get the structure right. Fund it completely. Review it regularly. And work with people who specialize in this because the difference between a good trust and a bad one isn’t the amount inside it. It’s everything else.
What is the single biggest mistake parents make when setting up a trust fund?
The single biggest mistake is creating the trust document but failing to fund it, meaning they never actually transfer their assets (property, accounts, investments) into the trust’s name. The result is that assets pass through probate at death instead of going directly to the child through the trust.
Do you need to be wealthy to set up a trust fund for a child?
No. Trust funds are useful for any parent who wants control over how and when their assets reach their child, wants to avoid probate, or wants to protect assets from creditors or divorce. You don’t need a large estate to benefit from a trust.
What’s the difference between a revocable and irrevocable trust?
A revocable trust can be changed or cancelled at any time during your lifetime, but it doesn’t provide estate tax benefits or strong creditor protection. An irrevocable trust is very difficult to modify once created, but removes assets from your taxable estate and provides significantly stronger asset protection.
How much does it cost to set up a trust fund?
A professionally drafted trust typically costs between $1,500 and $5,000 depending on complexity and your location. More complex multi-trust strategies can cost $5,000–$15,000 or more. This is a one-time expense that can save your estate far more in probate costs, taxes, and legal disputes.
What is a spendthrift clause in a trust?
A spendthrift clause prevents beneficiaries from assigning or transferring their interest in the trust before they actually receive distributions. This protects trust assets from the beneficiary’s creditors and prevents them from being seized in a divorce settlement or lawsuit.
How often should you update a trust fund?
At minimum every 2–3 years for revocable trusts, and immediately after any major life event: birth, death, divorce, significant change in assets, or a major change in tax law. Irrevocable trusts are harder to change, making the initial setup even more critical.
What is the federal estate tax exemption in 2026?
The federal estate and gift tax exemption increased to $15 million per individual ($30 million for married couples) as of January 1, 2026, under the One Big Beautiful Bill Act. The annual gift tax exclusion remains $19,000 per recipient in 2026.
Can a trust fund protect my child’s inheritance from divorce?
Yes, if the trust is properly structured with appropriate protective provisions. Without specific protective language, inherited assets may be treated as marital property in some states. A spendthrift clause and careful trust drafting can significantly reduce this risk.
Note: This article is for informational purposes only and does not constitute legal or financial advice. Trust law varies significantly by state. Consult a licensed estate planning attorney and qualified tax advisor for advice specific to your situation.